The Central Bank raised its base rate to 3.9% following the US Federal Reserve’s first hike since 2023. Whether you have a mortgage, a loan, a credit card or just savings sitting in a bank account, this affects you.
Nobody particularly enjoys hearing that interest rates have gone up. It is the kind of news that lands in your inbox on a Thursday morning and immediately makes you think about your mortgage, your car loan, your credit card balance and whatever you have sitting in a savings account roughly in that order.
Related Stories
This week, that Thursday morning arrived for UAE residents.
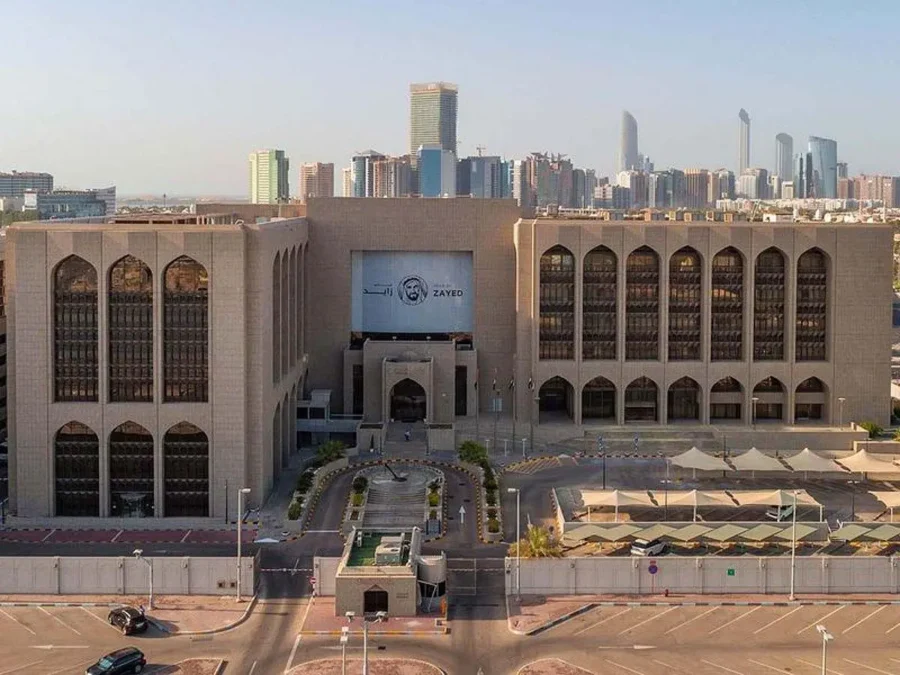
The Central Bank of the UAE raised its base rate by 25 basis points to 3.9%, effective September 17th, following the US Federal Reserve’s decision to lift its target range to 3.75 to 4 percent the first rate increase since 2023. The UAE’s move was widely expected, immediate and consistent with how the country has always handled Federal Reserve decisions. When the Fed moves, the UAE follows. That is not a coincidence it is monetary policy by design.
It All Comes Down to the Dirham-Dollar Peg
The relationship between UAE interest rates and US Federal Reserve decisions is not complicated once you understand one thing, the UAE dirham is pegged to the US dollar. That peg has been in place for decades and is one of the most stable currency arrangements in the world. But stability comes with a condition. To maintain that peg credibly, the UAE Central Bank keeps its base rate closely aligned with whatever the Federal Reserve is doing.
When the Fed raises rates, as it did this week, citing inflation that remains stubbornly above its 2 percent target the UAE Central Bank raises its own base rate in the same direction. When the Fed cuts, the UAE typically follows downward. The base rate itself signals the general direction of monetary policy and provides a floor for overnight money market rates across the country.
What this means practically is that decisions made in Washington by Federal Reserve Chair Kevin Warsh directly influence the cost of borrowing in Dubai, Abu Dhabi and every other emirate. The rate hike felt in New York on Wednesday was felt in the UAE by Thursday.
If You Have a Mortgage, Read This Carefully
Mortgage holders are among the first group to feel the practical consequences of a rate change, but the exact impact depends entirely on what kind of mortgage you have. Fixed-rate mortgage holders can breathe for now. If your rate is locked in for a defined period, that rate does not change until the fixed term ends. Your monthly payments stay exactly where they are until your lender reviews them at the next scheduled interval.
Variable-rate mortgage holders are in a different position. These loans are typically tied to benchmark rates that move with the broader market. As the base rate climbs, the rate applied to a variable mortgage can be adjusted upward when it comes up for review. If you are on a variable rate, the question to ask your bank right now is when your next review date is and what formula governs how your rate is calculated.
For anyone looking to take out a new mortgage, the environment has shifted. Higher base rates filter through the financial system and make new borrowing more expensive. Banks still set their own product pricing and a 25-basis-point central bank increase does not translate identically across every mortgage product on the market but the general direction is upward, and shopping around between lenders matters more in a rising rate environment than it does when rates are stable
Car Loans, Personal Loans and the Broader Borrowing Picture
The same logic applies across other forms of borrowing. Existing fixed-rate personal loans and car loans are insulated from the rate move the cost was agreed upfront and stays fixed for the life of the loan. Existing variable-rate personal debt may see costs adjust at the next review. For anyone planning to finance a significant purchase a vehicle, a home renovation, anything requiring a new loan the cost of that credit is higher today than it was last week. The difference on a single loan may seem modest. Across a large loan over a multi-year repayment period, the cumulative effect is considerably more significant.
One thing worth understanding clearly, banks do not apply central bank rate changes uniformly or immediately across all products. Two banks can offer meaningfully different rates on the same loan type in the same week. Comparison remains the most practical tool available to any borrower in this environment.
Credit Cards Are Not Automatically Affected — But the Environment Has Shifted
Credit card rates are governed by individual product terms rather than automatically adjusting whenever the central bank moves. A 25-basis-point base rate increase does not mean every cardholder wakes up Thursday to find their card charging more. What it does mean is that the broader cost of credit is moving higher. Anyone carrying a significant balance on a variable-rate card should keep an eye on their card terms and any communications from their bank about rate adjustments. The headline central bank number is less relevant than the specific terms of whatever financial product you are actually using.
The One Group That Benefits From Higher Rates
Not everyone loses when rates rise. Savers people keeping money in savings accounts or fixed deposits may find banks offering more attractive returns as rates move higher. The key word is may. Banks choose independently how much of a rate increase they pass through to depositors. Some move quickly. Others are slower. Fixed deposit rates tend to respond more reliably than standard savings account rates.
If you have cash sitting in a low-yield account, this week’s rate move is a genuine prompt to check what your bank is currently offering on deposits, and whether better terms are available elsewhere.
What This Means for Dubai’s Property Market?
Higher interest rates carry specific implications for Dubai’s property market, which has been running at remarkable pace for several years. For cash buyers who represent a significant proportion of Dubai’s luxury and premium segment transactions a rate move changes very little. They are not borrowing and their purchasing power is unaffected.
For mid-market buyers relying on mortgage financing, the picture is more pressured. Monthly repayment costs on new mortgages will be slightly higher. Affordability calculations that made sense at a lower rate need revisiting. In a market where property prices have already appreciated substantially, the addition of higher borrowing costs tightens the budget for a meaningful segment of potential buyers. Small businesses are also watching carefully. Refinancing existing debt becomes more expensive in a higher-rate environment, which tends to push companies toward protecting cash flow rather than investing aggressively in expansion.
The Bigger Picture, Oil Provides a Cushion
There is a counterweight to the pressure that rising US rates place on Gulf economies, and it sits in the ground. Higher global interest rates, historically, have been associated with a stronger US dollar, which can weigh on oil prices. But when rates rise in response to stubborn inflation rather than economic weakness, the picture is more nuanced. Gulf sovereign wealth funds and national development programmes remain well capitalised. The UAE’s diversification initiatives and Saudi Arabia’s Vision 2030 carry sufficient financial backing to absorb the impact of higher borrowing costs without fundamentally altering their trajectories.
For the UAE as a whole, the rate environment is tighter than it was a week ago. For most residents, the practical impact is modest and manageable. But knowing which side of the rate move you are on borrower or saver, fixed or variable, buying now or waiting makes a real difference to what this Thursday’s announcement actually costs you.